Tag: Jim Stanford

  • The PBO reveals just how much the Stage 3 tax cuts favour the wealthy

    Originally published in The Guardian on September 1, 2022

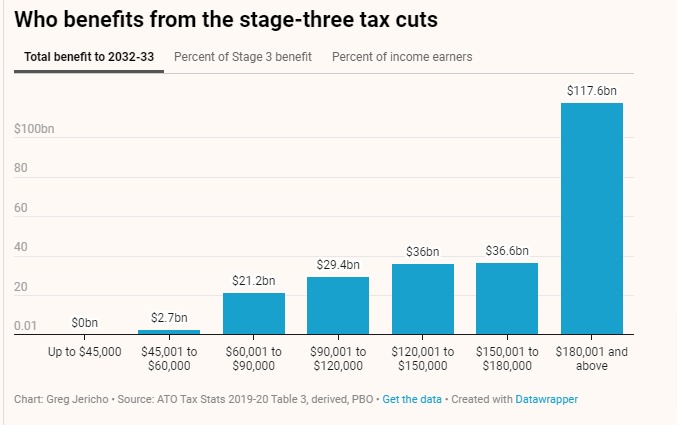
    The Stage 3 tax cuts, which will essentially create a flat income tax system, have always been clearly biased towards high-income earners. For those earning over $200,000, the tax cuts represent a 4.5% cut compared to just 0.6% for someone on the median income of $60,000. But this week, the Parliamentary Budget Office has released costings that detail just how skewed the allocation of money is to the richest in our society.

    As labour market and fiscal policy director, Greg Jericho notes in his Guardian Australia column, the PBO estimates that of the $243.5bn that the tax cuts will cost in their first 9 years, 48% will go to people earning over $180,000, and 77% will go to the richest 25%.

    In the first year of operation, the richest 1% of income earners will get the same benefit from the tax cuts as will the poorest 65%.

    Greg Jericho notes that in 2024-25, $12.7bn of the $17.7bn annual cost of the tax cuts that year will go to those earning above $120,000. That is almost the same amount expected to be spent on Jobseeker payments that year.

    The Stage 3 cuts are designed to favour the wealthy and reduce the level of revenue which in turn will force cuts to spending and programs that assist the most vulnerable.


    You might also like

  • The biggest real wages fall on record

    Originally published in The Guardian on August 18, 2022

    The latest wages price index figures from the Bureau of Statistics reveal just how far workers ability to purchase items with what they earn has fallen.

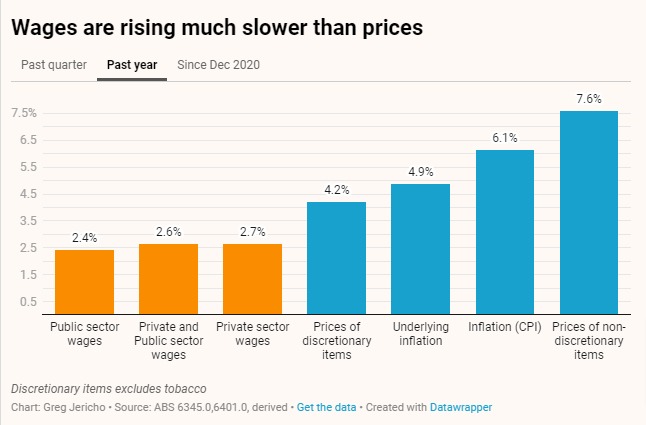
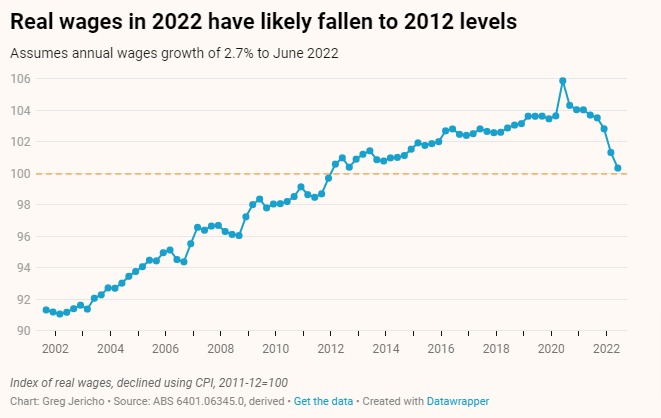
    In his column in Guardian Australia, Labour Market and Fiscal Policy Director, Greg Jericho, notes that while nominal wage grew 2.6% in the past year, real wages fell 3.3%. That fall has taken workers’ purchasing power back to 2012 levels.

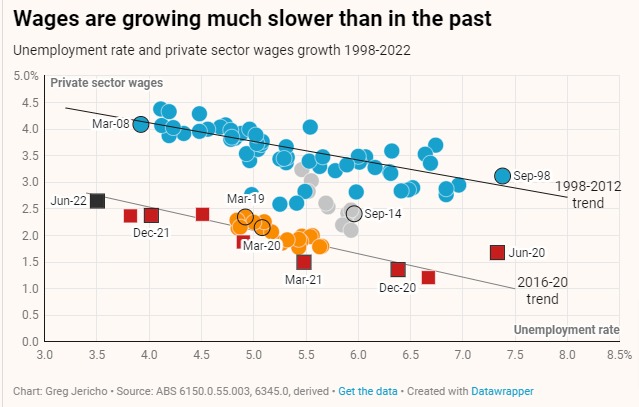
    This lack of strong wages growth despite unemployment being at nearly 50 year lows highlights just how skewed the bargaining system is against employees. In the past, unemployment this low would have been delivering wages well above 4%.

    The weak public-sector wages growth also reveals the impact of public-sector wage caps. For 6 consecutive quarters the annual growth of public-sector wages has been below that of the private sector. No longer does the public sector guide and support private-sector wages. This is the result of instituting arrangements which prevent a natural bargaining process to occur and in a time of rising inflation produce a massive fall in real wages for public-sector workers.

    In the past year wages in the education system, for example, rose just 2.3% on average, meaning teachers real wages fell 3.7% in the past year.

    While the real wages fall is terrible, it is likely worse for many families.

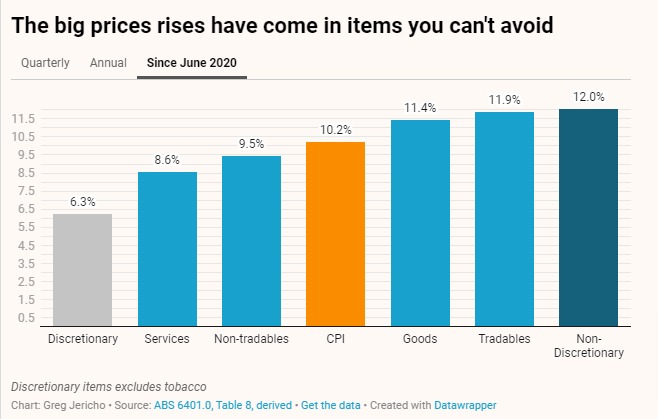
    The Bureau of Statistics estimates that households on average spend around 60% of their weekly expenses on essential/non-dictionary items. But because the prices of those items rose by 7.6% over the past year compared to average inflation of 6.1%, any households that need to spend a greater share of their income on essential items would have seen their real wages fall even further. For a family that spends 80% of their weekly budget on essential items, real wages fell by 4% – a truly horrific experience.

    The wages data confirm that there is no wages breakout that is driving inflation, instead workers are being left behind while companies produce record profits.

    The Jobs and Skills Summit in September must address this imbalance.


    You might also like

  • An Economy That Works for People

    An Economy That Works for People

    by Jim Stanford

    The new Commonwealth government is hosting a major Jobs Summit in September 2022, bring together representatives from a range of stakeholder groups to discuss the challenges facing Australia’s labour market, and how to achieve strong employment, job quality and security, and better skills and training opportunities.

    In preparation for the Summit, the Australian Council of Trade Unions is publishing a series of discussion papers to spark dialogue over key issues that will be discussed at the event. The first of these papers, on the failures of past macroeconomic policy and the need for better approaches, was prepared with input from Jim Stanford, Director of the Centre for Future Work.

    The 23-page report, titled An Economy That Works for People, first reviews the legacy of the last decade of one-sided macroeconomic and labour market policies from former Coalition governments. Boosted by government actions to reduce taxes, labour costs, and regulations, corporate profits have swelled to the highest share of GDP (almost 30%) in history. But that profit has not translated into investment or innovation: at present just 37 cents of each dollar in profit is reinvested in new projects. Meanwhile, the share of GDP going to workers has never been lower since records have been kept: falling to just 45% in 2022. This redistribution of income from workers to businesses is not just a moral failure. The impact of swelling profit margins on inflation, and the drain in spending power arising from uninvested profits, are holding back Australia’s economy considerably.

    An Economy That Works for People

    The paper discusses the causes and consequences of the current surge in inflation in detail, providing conclusive evidence the problem did not arise in the labour market. To the contrary, labour costs have servedto reduce inflation: nominal unit labour costs grew only 2.1% over the last 12 months (below the RBA inflation target), while unit profit margins surged (by over 14%).

    The paper also reviews statistical evidence on Australia’s productivity growth, and in particular on the failure of productivity growth to be reflected in rising real wages. Real put per hour of work has increased 13% over the past decade: not outstanding, but still positive and steady. Real wages, in contrast, have gone nowhere — and are now falling rapidly in the face of accelerating inflation. Rather than risking an economy-wide recession with rapid interest rate hikes (which impose the worst burden on workers and indebted households), the paper calls for a more multi-dimensional and targeted approach by government (supplementing actions by the RBA) to gradually bring inflation down without causing mass unemployment.

    The paper makes 6 specific recommendations for macroeconomic reforms to ensure working Australians share fairly in the benefits of future growth. The first is to elevate full employment in decent jobs as the central goal of macroeconomic policy, and to ensure that all policy interventions (including from the RBA, the Commonwealth government, and other regulatory agencies) are consistent with that top goal.

    Release of the paper generated extensive media coverage and public debate (which was its goal!): including stories in The Guardian, the ABCThe Sydney Morning Herald, The Australian Financial Review, and The Australian. In this feature interview with 2CC Radio host Leon Delaney, Dr Stanford discusses the main recommendations of the report, and whether it is really such a ‘radical’ idea to make full employment the top goal of economic policy:


    Full report

    Share

  • Interest Rate Hikes Will Hurt Workers to Protect Profits

    Interest Rate Hikes Will Hurt Workers to Protect Profits

    by Anis Chowdhury

    The Reserve Bank of Australia has hiked its interest rate 4 times so far this year, for a combined total of 1.75 percentage points. And it has signalled more increases are ahead, as it joins other central banks around the world in rapidly increasing rates to slow spending power, job-creation, and hence inflation.

    In this commentary, Centre for Future Work Associate Dr Anis Chowdhury challenges the wisdom of this strategy. Since current inflation is related more to supply chain disruptions and other global pressures, higher interest rates will do more harm than good – and shift national income even further toward the owners of capital, instead of working Australians.

    Interest Rates Hikes Will Hurt Workers to Protect Profits

    by Dr Anis Chowdhury

    The Reserve Bank’s latest interest rate hike, the fourth in a series and with more to come, will certainly slow economic activity and raise unemployment. It will hurt families, especially of the working class, who played no role in the current bout of inflation.

    Treasurer Jim Chalmers warned Parliament, “Families will now have to make more hard decisions about how to balance the household budget in the face of other pressures like higher grocery prices, and higher car prices and the cost of other essentials”.

    This is bad news, especially since many will also lose their jobs as the economy slows.

    But it didn’t have to be like this – had the RBA and other policy-makers cared to seriously consider what is driving inflation, and been less dogmatic about their inflation target and how to reach it. Many seem to have forgotten the Labor Government’s own successful experience of addressing inflation in the 1980s through social dialogue, reducing price pressures without causing unemployment to rise. Those lessons should be relearned today.

    What is driving current price rises?

    The primary source of current price pressure is not surging demand, soaring wages, or a household spending spree fueled by pent-up demand and one-off pandemic financial supports. Indeed, as RBA Governor Philip Lowe has acknowledged, “The household saving rate remains higher than it was before the pandemic and many households have built up large financial buffers”.

    Even the labour market tightening and skills shortages seen in some sectors are not the result of surging aggregate demand, but rather mostly due to the impacts of the pandemic on labour supply (including via restrictions on the inflow of migrant workers).

    Instead, the primary driver of current inflation is supply bottlenecks and blockages of goods, caused by a perfect storm of global problems: the pandemic, the war in Ukraine, and climate change’s effect on agricultural supply (and hence prices of food).

    Interest rate hikes cannot fix supply bottlenecks; instead, they will exacerbate supply problems, by discouraging investment in new capacity and infrastructure. Interest rate hikes will also impose collateral damages on government finance, in addition to causing job losses and economic hardship for struggling families.

    The Treasurer’s warning to brace for bigger real wage cuts than previously flagged is no comfort for the ordinary workers who already saw their income share in GDP steadily decline during the past four decades – while the share of GDP going to capital owners in profits continued to rise, setting record highs during the pandemic.

    A recent report from the Australia Institute found that rising prices in Australia are actually driving corporations’ profits to record highs amid a cost-of-living crisis for the rest of us. This has been enabled in large part by lack of competition. Big corporations in energy, transportation, supermarkets, and other sectors use their oligopolistic power to raise prices (and profits) far above what would be necessary simply to cover higher input costs.

    A recent study published in the UNSW Law Journal documented widespread price gouging in Australia: “a notorious practice” involving “pricing high-demand essentials at levels significantly higher than what is commonly considered acceptable, reasonable or fair”. During recent crises, including the Black Summer bushfires and then the COVID pandemic, unethical businesses exploited public desperation for basic consumer goods and services, such as hygiene products, staple foods, and utility services, to raise their profit margins.

    Why raise interest rates?

    The RBA knows it cannot fix supply shortages. Yet still it raises the interest rate, calls it a “forward-looking” strategy, and claims it will stem inflationary expectations and higher wage demands. Basically, this is a tactic to scare workers: in essence, saying to workers they must not ask for compensating wage gains or for restoring their share of domestic income, lest the Bank inflict more pain through losing jobs and livelihoods.

    Central bankers around the world sugar-coat this scare tactic by saying, “It’s short-term pain for long-term gain”. That’s easy for them to say, as no central banker ever lost his/her job for such actions, or have tasted this “short-term pain” (which can actually affect a worker and their family for decades via lost work and suppressed incomes).

    This view also ignores the fact that labour’s bargaining power has significantly declined compared to previous inflationary episodes, due to the erosion of collective bargaining and other institutional supports for wages, new technology, out-sourcing and globalisation. All these factors have driven the steady declines in labour income share and real wages. They also mean that fears of a 1970s-style “wage-price spiral” are not credible.

    The interest rate: a blunt tool

    The dogmatic stance of central bankers will cause more damage than it avoids. Even when inflation is rising, higher interest rates are not the right policy tool to tackle the problem for several reasons.

    First, the interest rate only addresses symptoms, not the root causes, of inflation. Inflation is often understood as the overheating of an economy. Like a fever, overheating of an economy can be due to many causes – fever and overheating are just symptoms. Interest rates, like Panadols or Aspirins, may relieve the overheating, but the treatment requires investigations into the root causes and appropriate medications.

    Second, changes in the interest rate affect all sectors – without distinguishing sectors that need expansion and hence credit support, from sectors that are less productive or inefficient and hence should be credit-constrained. Just as taking too many Panadols or Aspirins can have fatal side effects, hiking interest rates too often and too high can kill productive and efficient businesses along with less productive and inefficient ones.

    Third, the overall interest rate does not distinguish between households and businesses. Higher interest rates may encourage households to save, but will dampen business capital spending. Thus, overall economy-wide demand will shrink, discouraging investment in new technology, plant and equipment as well as skill-upgrading. Thus, higher interest rates adversely affect the long-term productive capacity of an economy.

    Fourth, higher interest rates will raise the debt burden for governments, business and households. Global debt burdens have been on the rise since the 2008-2009 global financial crises, and even more dramatically during the COVID crisis. Those debts (especially sovereign government debts) are manageable so long as economic growth remains robust and interest rates low. Current monetary policy, however, will negatively affect both factors: raising rates and slowing growth. That could set the stage for debt problems down the road.

    Monetary tightening will have implications for fiscal policy, too. A slower economy implies less tax revenues and more social security payments. Government is already under pressure to continue pandemic support measures, such as financial assistance for workers without paid sick leave as well as cost-of-living supports. Planned Stage Three tax cuts, if they go ahead, would further undermine Commonwealth government revenues. For state governments, heavily reliant on stamp duties, a collapse of the housing market would devastate their budget bottom-lines.

    Paradoxically, higher interest rates can even feed into higher costs of living, as indebted households’ debt-servicing costs (especially on mortgages) rise. The cost of living would also rise if businesses with market power pass on their own higher interest costs to consumers through still higher prices.

    Policy innovation

    As mentioned earlier, the current inflationary surge is due to supply shortages of key products, such as food and fuel. Therefore, the long-term solution requires expansion of supply and removal of bottlenecks. Perversely, however, higher interest rates force overall demand to shrink down to match aggregate supply. That can slow price increases, but leaves underlying supply constraints for key products unaddressed – hence not addressing the underlying causes of inflation.

    Therefore, policymakers should consider innovative and more appropriate policy tools to respond to current price pressures. The focus of anti-inflationary policy should be changed radically from suppressing domestic demand to enhancing supply and productivity; from restricting credit indiscriminately to easing financing constraints for key and ‘sun-rise’ industries (e.g., renewable energy) while tightening financial conditions for inefficient (e.g., polluting) and speculative activities (e.g., real estate).

    This would mean designing macroeconomic policies to support industrialisation and economic diversification. Instead of reacting to inflationary symptoms with a lone blunt policy tool (the interest rate), policymakers should wield a mix of fiscal and monetary policy levers: using them to unlock supply bottlenecks, enhance productivity, and encourage savings and productive investments (especially to decarbonise the economy).

    Each of these goals needs innovative and customised policy tools, rather than a one-size-fits-all reliance on interest rates to throw cold water over the entire economy.

    Social partnership

    Inflation and responses to it inevitably involve social conflicts over economic distribution. The ‘social dialogue’ approach of Labor Prime Minister Bob Hawke contrasted with the more confrontational approaches of Margaret Thatcher and Ronald Reagan – and their deliberate use of punishing interest rates to inflict long recessions in the 1980s.

    In contrast, social dialogue in Australia not only brought down inflation and unemployment simultaneously in the 1980s, but also enabled difficult reforms – including floating exchange rates and lower import tariffs. That set the stage for sustained economic growth in years to come.

    The new Labor Government needs to earnestly begin rebuilding that model of social partnership to confront not only current inflation challenges, but the more existential threats of climate change and shifts in the global order.

    The government must also not miss the opportunity to review the RBA’s mandate and operations, including better balancing its board with a more representative variety of stakeholders (including workers). The economy does not work in a vacuum, and should not be entrusted to technocrats. Policies and reforms affect real lives and livelihoods. The RBA needs to understand, and hear, the voices and preferences of all Australians, not just financiers and employers.

    You might also like

  • A decade of real wages growth lost as prices soar ahead of wages growth

    Originally published in The Guardian on July 28, 2022

    The latest inflation figures from the Bureau of Statistics reveal just how much workers have been left behind. Writing in Guardian Australia, labour market and fiscal policy director Greg Jericho notes that while the focus is on the biggest annual increase in inflation since the introduction of the GST, the data also shows that real wages have fallen drastically.

    Given prices grew 6.1%, but wages are expected only to achieve around 2.7% growth in the 12 months to June, it remains abundantly clear that inflation is not being driven by labour costs. Indeed given real wages have likely fallen around 3.4% in the past year, wages are currently extremely deflationary.

    Real wages have now fallen for 8 consecutive quarters sending the purchasing power of employees back to 2012 levels.

    While the economy has rebounded and profits have risen strongly with that of prices, the “recovery” from the pandemic has very much been on the backs of workers who have effectively lost a decade’s worth of growth in real wages.

    Even worse, given the greatest price rises have occurred for essential commodities, it is clear low to median income workers are hurting much more than those who devote less of their spending on essentials than does the average household.

    All this is occurring with unemployment at near 50-year lows. It is now abundantly clear that the labour market systematically disempowers employees and needs to be reformed.


    You might also like

    Dutton’s nuclear push will cost renewable jobs

    by Charlie Joyce

    Dutton’s nuclear push will cost renewable jobs As Australia’s federal election campaign has finally begun, opposition leader Peter Dutton’s proposal to spend hundreds of billions in public money to build seven nuclear power plants across the country has been carefully scrutinized. The technological unfeasibility, staggering cost, and scant detail of the Coalition’s nuclear proposal have

  • Profits push up prices too, so why is the RBA governor only talking about wages?

    Originally published in The Conversation on June 27, 2022

    Reserve Bank of Australia governor Phillip Lowe has invoked memories of the 1970s, warning wage growth must be restrained to contain Australia’s surging inflation.

    In the 1970s, Lowe said last week, “we got into trouble because wages growth responded mechanically to the higher inflation rate”. Now, with inflation above 5%, and tipped to reach 7% by the end of the year, he wants want people to keep in mind an “anchoring point” for wage growth of 3.5%.

    That 3.5% represents the central bank’s long-standing judgement that wage growth equal to the RBA’s ideal inflation target (2.5%) plus productivity growth (typically more than 1% a year, currently above 2%) is economically sustainable.

    Lowe says “if wage increases become common in the 4% and 5% range” that will make it harder to get inflation back to his target. But that prospect seems so remote it’s a wonder why he focused on it. Particularly when he said nothing about about the role of ever higher profits on increasing prices.

    Wages increases aren’t the problem.

    Nominal wage growth has languished well below that 3.5% benchmark since 2012. The last time wages grew at more than 4% was 2009.

    Over the past decade, wages have fallen further and further behind the level implied by the RBA’s magic formula. During this time Lowe (governor since 2016) repeatedly cited weak wages as a key factor keeping inflation below the bank’s 2-3% target – but nothing happened.

    So why is he now ringing alarm bells about wages growing too fast? It’s not at all clear when broad wage growth will even regain 3.5%, let alone surge faster.

    The Fair Work Commission’s decision this month to raise the minimum wage by 5.2% and wages for other award-covered workers by 4.6% will boost the pay for about a quarter of workers. But even that can’t be considered “inflationary” by any stretch of imagination. In real terms, the minimum wage will fall again this year, as it did last year.

    Most other workers have little chance of doing as well.

    Wage gains from enterprise bargaining agreements (covering about 35% of workers) remain subdued. In the latest 12-month period they delivered an average increase of just 2.6%.

    For the 38% of workers on individual contracts – now the most common pay-setting method in Australia’s individualised labour market – there is even less reason to expect wage growth to suddenly accelerate.

    Profits have played a bigger role

    Labour is not the only component in production costs: a considerable profit margin is also built into final prices. In fact, after decades of capital’s share of GDP increasing while labour’s declines, those profits have become more important in price-setting.

    That’s a big change from the 1970s, when the narrative about wage-driven inflation became so firmly locked into the national policy discourse.

    Indeed, by the end of 2021, corporations made 62 cents in gross profit for every dollar they paid in labour compensation. That’s the highest in history – and more than twice the rate in the 1970s.

    Yet while the RBA warns darkly about rising labour costs, the growing importance of profits in driving higher prices is not mentioned. This reflects an ideological bias that wages are a “cost” item that must be tightly controlled, while profit is assumed to be a legitimate “reward” to businesses that efficiently supply the market with something valuable.

    Calculating profit costs
    The Australian Bureau of Statistics calculates several measures of unit labour costs – the cost of employing labour per “unit” of production. It does not publish a measure of “unit profit cost” – what gets paid in profit per unit of production. But perhaps it should. That might motivate greater attention to the role of profit margins in current inflation.

    In lieu of ABS data, however, we can create a broad measure of unit profit cost by comparing the growth of nominal corporate profits to the growth of real output (similar to the methodology for measuring unit labour costs).

    As shown in the following graph, since the start of the COVID-19 pandemic unit profit cost has surged 24%, compared with a 4% increase in the nominal unit labour cost (which, being over two years, is still below the RBA’s inflation target.

    Blaming the victims
    Warnings about wages misdiagnose the source of current inflation. They blame the victims of falling real wages for a problem they did not cause.

    The RBA acknowledges the upsurge in inflation was initially fuelled by COVID-19 disruptions – including supply chain problems, global energy prices and major (but temporary) shifts in the composition of consumer demand.

    But corporations with pricing power (particularly potent in sectors like energy, housing and groceries) took advantage of those disruptions to fatten their profit margins. They have profited from inflation, while workers lost out.

    Now workers are being told they must swallow further real wage cuts to fix the inflation that enriched their employers.

    Once the RBA confronts the issue of inflated profits as both a cause and a consequence of current inflation, we then might discuss labour’s role. Until then, workers are justified in fighting to protect their real incomes.


    You might also like

    Dutton’s nuclear push will cost renewable jobs

    by Charlie Joyce

    Dutton’s nuclear push will cost renewable jobs As Australia’s federal election campaign has finally begun, opposition leader Peter Dutton’s proposal to spend hundreds of billions in public money to build seven nuclear power plants across the country has been carefully scrutinized. The technological unfeasibility, staggering cost, and scant detail of the Coalition’s nuclear proposal have

  • Unemployment Rate Does Not Tell the Whole Story

    Unemployment Rate Does Not Tell the Whole Story

    by Anis Chowdhury

    Three days before the federal election, new ABS data confirmed that Australian wage growth is still stuck at historically weak rate (up just 2.4% year over year to March 2022). One day later, another ABS release showed another small decline in the unemployment rate, which is now below 4%. Most of the decline was due to people leaving the labour market (rather than new jobs being created). But the data is being cited by the current government as a sign that better wage growth is just around the corner.

    In this commentary, CFW Associate Dr Anis Chowdhury explains why a lower unemployment rate, on its own, is not a solution to Australia’s labour market and social challenges.

    Don’t Be Fooled: A Lower Unemployment Rate is Not a Magic Bullet

    Two days before the federal election, comes news that Australia’s unemployment rate had slipped below 4% in March, to 3.9% – the lowest rate in 48 years.

    But this aggregate number hides some hard realities for struggling vulnerable people. For example, the youth unemployment rate increased to 8.8%. About 3 million Australian workers lack basic job security. That includes some 2.4 million workers in casual positions, with no paid leave entitlements. A further 500,000 are on fixed-term contracts. A survey by PwC found that anxiety about the economic future intensified due to the pandemic. Some 56% of Australians now believe few people will have stable, long-term employment in the future (more than two years).

    Meanwhile, the labour force participation rate decreased to 66.3% in March as workers continue to suffer from the pandemic’s scars – including mental health challenges and long COVID’s debilitating health issues. So this apparent labour market tightening is misleading: it is mainly due to this decline in the participation rate, as well as pandemic restrictions on migrant workers (including students and seasonal travellers) which have sharply constrained the size of Australia’s labour force.

    Most telling, Australia’s recent falling unemployment rate is having little effect on wages growth; wages grew 2.4% in the year to March, up only marginally on the 2.3% from the previous reading; and less than half the 5.1% rate of inflation.

    Rising interest rates will now deliver a further blow to the living conditions of ordinary citizens as they struggle to service their debts. With household debt equal to about 120% of annual GDP, Australian households are among the most indebted in the world. As the Reserve Bank is poised to raise interest rates further, Andrew McKellar of the Australian Chamber of Commerce has warned that Australians “have to be very careful”; interest rate hikes are “set to affect Australian businesses nationwide across a number of sectors”.

    So it’s not being alarmist to warn that a recession could be just around the corner: one that would see unemployment rising alongside inflation. The Reserve Bank has little control over the factors (mainly global supply chain disruptions, and rising food and fuel prices) that have led the current cost-of-living inflation. Past history suggests that central banks’ efforts to disinflate the economy produce slower growth, higher unemployment, and often recessions.

    Address the deeper malaises

    No matter who wins the current federal election, the incoming government will have to tackle deeper malaises in the Australian economy. They include stagnating productivity growth and the falling labour income share in GDP.

    Australia’s aggregate labour productivity growth (real output per hour) has stayed mainly in a band between 1.2 and 2.5% per year during the last 50 years; it fell to 0.2% during 2018-2019, but has rebounded since the pandemic (averaging 2% per year from end-2019 through end-2021). Productivity growth is a key source of long term economic and income growth, and as such, is an important determinant of a country’s average living standards. Productivity gains also drive down the cost of goods and services and enhance international competitiveness.

    The impact of productivity growth on standards of living has been undermined, however, by capital’s capture of productivity gains. Real wages have grown much more slowly than real labour productivity (and now, with surging inflation, real wages are falling rapidly). Thus, labour income’s share in Australia steadily declined from the peak of around 58.5% in the mid-1970s to a record low of 46% of GDP at end-2021, as the gap between productivity growth and real wage growth widened.

    Among many factors, wage-suppressing policies and increased job insecurity have contributed to this dismal outcome. More than half of Australian participants in the PwC survey (61%) felt the government should act to protect jobs, with that opinion more acute among 18-34 year-olds (63%) than those over 65 (50%).

    Both the Reserve Bank of Australia and Treasury have made clear, Australia’s low wage growth is a major drag on the economy. But low wage growth was not accidental; the former Coalition Finance Minister, Matthias Cormann, now OECD Secretary-General, described (downward) flexibility in the rate of wage growth as “a deliberate design feature of our economic architecture”.

    Looking after workers is good economic policy

    Coalition leaders attacked Labor leader Albanese’s support for raising the minimum wage, claiming without evidence that a big increase in the minimum wage might force some workplaces to close. The business lobbies also joined the chorus.

    But is this opposition to higher wages grounded in good economics? The available historical evidence, as well as theoretical considerations, say: “no”.

    Robert Bosch, the German industrialist, engineer and inventor, founder of Robert Bosch GmbH (electrical co), introduced 8-hour working days in 1906, free Saturdays in 1910, and other benefits for his workers. He said: “I don’t pay good wages because I have a lot of money; I have a lot of money because I pay good wages.”

    Henry Ford, the American industrialist, the founder of the Ford Motor Company, and developer of the assembly line, doubled the pay of his workers to $5 a day in 1914. In justifying his decision he said: “Of course the higher wage drew a more productive worker.  But that wasn’t the real reason. The fact was, it was no good mass-producing a cheap automobile if there weren’t masses of workers and farmers who could afford to buy it.”

    Both Bosch and Ford realised that better pay and working conditions attract better workers and raise their productivity. They also knew that better pay and working conditions also lead to higher sales and revenues. Therefore, overall profit rises despite a higher labour cost. It is no wonder that both their companies not only survived but also became leading global companies.

    Singapore, which began its industrialisation by initially taking advantage of cheap labour, has used a deliberate high-wage policy since the early 1980s to move toward high value-added activities. It thus maintained its dynamism not by cutting wages and working conditions, but by incentivising companies (in part through higher wages) to upgrade skills and technology, and hence improve productivity.

    In other words, regular upward adjustment of wages can be an effective industry policy tool for accelerating innovation, upgrading, and productivity. Hence, higher wages and better working conditions do not necessarily cause loss of competitiveness in the international market.

    Industry-wide bargaining can boost productivity and real wages

    More than half a century ago two leading Australian academics – WEG Salter and Eric Russel – argued for tying wage increases in any industry to productivity trends across the whole industry, through a system of industry-wide bargaining. By adhering to industry-wide average productivity-based wage increases, they argued, industry bargaining raises relative unit labour costs of firms with below-industry-average productivity, thereby forcing them to improve their productivity or else exit the industry. At the same time, firms with above-industry-average productivity enjoy lower unit labour costs, hence higher profit rates for reinvestment – favouring the growth of more efficient firms. As mentioned earlier, Singapore used this approach to restructure its industry in the 1980s towards higher value-added activities, with great success.

    In contrast, trying to compete on the basis of low wages is a recipe for failure. Low-wage countries typically demonstrate lower productivity; and research by a leading French economist, Edmond Malinvaud, showed that a reduction in wage rates has a depressing effect on capital intensity.

    Salter’s research implies that the availability of a growing pool of low paid workers makes firms complacent with regard to innovation and technological or skill upgrading. Under-paid labour provides a way for inefficient producers and obsolete technologies to survive. Firms become caught in a low-level productivity trap from which they have little incentive to escape – a form of ‘Gresham’s Law,’ whereby bad labour standards drive out good. The discipline imposed on all firms as a result of negotiated industry-wide wage increases forces all of them to innovate and become more efficient.

    Need wide-ranging policy shifts

    Of course, industry-wide bargaining alone cannot solve all the problems of wage inequity or wage stagnation. It must be part of a broader suite of policy measures, to provide all-round support for greater equality and inclusive prosperity.

    For example, the next government should also address the system that produces sky-rocketing executive pay at the expense of workers. The annual CEO pay survey shows a drastic jump of an average of 24% during the pandemic, with annual bonuses soaring by 67% – the highest increase in recent record, while workers are suffering real income losses.

    A lower marginal tax rate is one of the incentives for the executives to pay themselves heftily, but tax cuts are not found to boost growth or employment. Share options for CEOs, which encourage job cuts and discourage re-investment, also must be reined in.

    If anything is making the Australian economy vulnerable, it is the growing economic disparity between self-serving executive compensation and stagnant wages for the rest of the population.


    You might also like

  • More Resources on Australia’s Wages Crisis

    More Resources on Australia’s Wages Crisis

    Share

    The debate over wages, prices, and living standards heated up even further this week, with the release of new ABS statistics showing continuing weakness in wages despite the acceleration of inflation. The latest data from the ABS Wage Price Index (WPI) shows nominal wages grew just 2.4% over the 12 months ending in March. That is less than half as fast as consumer prices grew (5.1%), producing the biggest decline in real wages this century.

    Our Centre continues to develop resources documenting the dimensions and causes of declining real wages, and countering the claim that trying to protect real living standards (by boosting wages at least as fast as inflation) will somehow cause hyperinflation and economic ruin.

    Our new landmark report, The Wages Crisis: Revisited, provides comprehensive data on the scale of Australia’s wage slowdown – which began in earnest around 2013. Even after the dramatic events of the COVID-19 pandemic, and the surprising decline in the official unemployment rate (now slightly below 4%), wage growth has only regained the same sluggish pace demonstrated for several years before COVID. And with consumer price inflation accelerating, weak nominal wage growth is now corresponding to major erosion in real wages.

    The three authors of that report – Prof Andrew Stewart from the Adelaide Law School, Assoc Prof Tess Hardy from Melbourne Law School, and the Centre for Future Work’s Director Jim Stanford – participated in a webinar hosted by our colleagues at the Australia Institute. They reviewed the main findings of the report, and answered several questions from the audience about the wages crisis and possible solutions. The webinar was hosted by Ebony Bennett, Deputy Director of the Australia Institute.

    Our team has also been working to analyse the implications of the latest wages data for real incomes, macroeconomic performance – and the federal election, in which wages have emerged as a major point of contention. Please see the following analysis from our team:

    Our team will continue to research the dimension, causes, consequences, and potential solutions to the worsening wages crisis in the coming weeks — no matter who wins Saturday’s election!


    You might also like

  • Real wages are shrinking, these figures put it beyond doubt

    Originally published in The Conversation on May 18, 2022

    Every three months the Bureau of Statistics releases the lesser-known cousin of the consumer price index. It’s called the Wage Price Index (WPI) and it records changes in the overall level of wages, in the same way the price index records changes in the overall level of consumer prices.

    Read the full article Real wages are shrinking, these figures put it beyond doubt on The Conversation.


    You might also like

    Denying Wages Crisis Won’t Make It Go Away

    by Jim Stanford

    As the great novelist Isaac Asimov wrote, “The easiest way to solve a problem is to deny it exists.” Business leaders and sympathetic commentators have adopted that advice with gusto, during current public debates over the unprecedented weakness of Australian wages.

  • Working With COVID: Insecure Jobs, Sick Pay, and Public Health

    Working With COVID: Insecure Jobs, Sick Pay, and Public Health

    by Dan Nahum and Jim Stanford

    Almost one in five Australians (and a higher proportion of young workers) acknowledge working with potential COVID symptoms over the course of the pandemic, according to new opinion research published by the Centre for Future Work.

    The research confirms the public health dangers of Australia’s existing patchwork system of sick leave and related entitlements.

    The main findings of the report, based on a poll of 1000 Australians, include:

    • More than one in three (37%) employed Australians have no access to statutory paid sick leave entitlements (including workers hired under casual employment arrangements, and self-employed workers). Another 12% had access only to pro-rated part-time entitlements.
    • When the pandemic hit Australia, barely half (51%) of employed workers could count on regular full-time income if they had to stay home from work.
    • Almost one in five respondents (19%), and a higher proportion of young workers (29%), acknowledged working with potential COVID symptoms at some point during the pandemic. This confirms the public health dangers of Australia’s patchwork system of sick leave and related entitlements.
    • Polling results also confirm that a significant proportion of workers (17%) also attended work after exposure to someone possibly infected with COVID.
    • Given inadequate sick pay entitlements and the surprising share of workers attending work in violation of public health advice, it is not surprising that 18% of workers did not feel safe attending their normal workplaces during the pandemic.

    This research indicates that Australia’s sick pay entitlements are clearly inadequate to protect workers’ health and safety at work and allow them to stay home from work when health advice requires it. The expansion of non-standard and insecure forms of work (including part-time work, casual jobs, contractor positions, and ‘gigs’) has heightened concern that many workers do not have the effective ability to stay home from work for health reasons.

    Government should expand sick pay entitlements to cover all workers, and also implement strategies to limit and reduce the incidence of insecure work: including by constraining employers’ use of ‘permanent casual’ arrangements, sham contracting, and on-demand gigs, none of which provide normal and healthy paid leave entitlements.

    Unfortunately, the current federal Government has done the opposite by reinforcing this shift toward insecure working arrangements – including through its 2021 amendments to the Fair Work Act, which cemented and expanded employers’ rights to hire workers on a casual basis (with no sick pay) in virtually any job they wish.


    Full report

    Share