Tag: Fiona Macdonald

  • Budget’s Illusory Hope for Business-Led Recovery

    Budget’s Illusory Hope for Business-Led Recovery

    by Jim Stanford

    Share

    The Commonwealth government tabled its 2020-21 budget on 6 October, six months later than the usual timing because of the dramatic events associated with the COVID-19 pandemic and resulting recession. There is no doubt it is a budget unlike any other in Australia’s postwar history. While the budget certainly unleashes unprecedented fiscal power, its underlying logic and specific policy design are unsatisfactory in many ways. We present here analysis and commentary on several aspects of the budget, drawing on input from all of the Centre’s research staff: Economist and Director Dr. Jim Stanford, Senior Economist Alison Pennington, and Economist Dan Nahum.

    Key conclusions of our analysis include:

    • This budget says explicitly that Australia’s economic reconstruction after COVID-19 is to be trusted almost entirely to private business – helped along with generous tax cuts and business subsidies.
    • The need to strengthen public services (like health care, child care, and higher and vocational education) is largely ignored, as is the need to preserve and strengthen income security programs (with the phase-out of JobKeeper and cuts to JobSeeker going ahead).
    • Tax cuts, whether targeted at businesses or high-income households, will have little impact on actual spending and job-creation.
    • The government needs a more forceful, hands-on, and sustained reconstruction plan to ensure that the economy does not get ‘stuck’ in its current state of partial recovery. That needs much more public sector leadership, vision, and funding.
    • The government admits that wage growth is going to get weaker before it gets stronger – but is doing nothing about that critical problem (which will undermine consumer spending far more than tax cuts will stimulate it).

    Download our full review of the 2020-21 budget below.


    Related documents


    2020-21 Budget Analysis

    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Centre For Future Work to evolve into standalone entity

    The Centre for Future Work was established by the Australia Institute in 2016 to conduct and publish progressive economic research on work, employment, and labour markets. Supported by the Australian Union movement, the centre produced cutting edge research and led the national conversation on economic issues facing working people: including the future of jobs, wages

  • Austerity Threatens Women’s Access to Paid Work

    Originally published in The New Daily on June 25, 2020

    Women have suffered the worst labour market impacts since the shutdowns. Gender-unequal impacts have been due to women’s greater exposure to customer-facing industries shut down first by public health orders, higher employment intensity in insecure and part-time positions, and an increased caring burden unmet by the state. But instead of providing countervailing support, the federal government is accelerating women’s work crisis.

    In this commentary, originally published in the New Daily, Senior Economist at the Centre for Future Work Alison Pennington outlines how government’s austerity agenda has intensified the unequal jobs fallout and threatens to “turn back the clock” for women’s economic security.

    How the government is turning back the clock for women

    The increase in women’s workforce participation is the most significant labour market trend of the past 40 years.

    However, in the COVID-19 health and economic crisis, the gender boundaries of paid work are being redrawn.

    Worse still, the government is the one holding the pen.

    Women have suffered the worst labour market impacts since the shutdowns.

    Total employment fell by 7.3 per cent for women compared with 5.7 per cent for men between February and May.

    About 450,000 women have lost their jobs and 350,000 left the labour market all together.

    Women saw a 12 per cent decline in hours worked, compared to 9 per cent for men.

    This gender inequity stems from three main channels:

    This combination has created a ‘perfect storm’ for women in the workplace.

    However, instead of stepping up to provide countervailing support, the federal government is only exacerbating the crisis.

    This started back when JobKeeper was announced and excluded short-term casuals by design, which affects more women than men.

    And then, most recently the government targeted early JobKeeper cuts to childcare workers in what is a cruel double blow.

    Not only do more women work in child care, but more women benefit from access to affordable child care.

    The cumulative impact of Australia’s effective gender pay gap of 32 per cent (in average weekly earnings for all workers) and inadequate parental leave supports for cash-strapped families makes their work-care decisions clear cut.

    Without affordable child care, mum’s got to stay home.

    There’s more bad news on the industrial relations front.

    Last week the Fair Work Commission decided to freeze minimum wages for up to seven months, in the sectors with the lowest wages and most precarious jobs – which are, surprise, mostly women’s jobs.

    While women have been bearing the brunt of the economic impacts of COVID19, state and federal governments have targeted stimulus spending on the most bloke-heavy industry in the economy – construction.

    For every $1 million invested in construction only 0.2 direct jobs are generated for women.

    Yet $1 million invested in education generates almost 11 jobs for women.

    In fact, education investment creates more jobs for just women than construction creates for anybody: Man or woman.

    Job-generating spending for women is best directed to the public sector.

    Women make up 61 per cent of all public sector workers, with the sector supporting fuller female participation – women hold 54 per cent of full-time roles but only 35 per cent of full-time roles in the private sector.

    Not only would public sector pay cuts risk driving this recession into a depression, they disproportionately hurt women’s incomes.

    Even temporary wage freezes (of one or two years) compound into tens of thousands of dollars in lost wages compounding over her working life.

    And austerity pain radiates far beyond income losses for affected workers, reducing consumer spending (right when the economy needs more), tax revenues and enhancing deflation risk.

    When the largest employer in the economy cuts wages, it has a powerful effect for other employers.

    It’s not just a hunch, this is exactly what happened after the GFC.

    The unnecessary 2011-12 federal public sector wages caps cut the legs out from everyone’s wages.

    But the pain induced from pay cuts doesn’t end there. Because lower-wage environments breed insecure work.

    People accept lower-quality jobs or juggle multiple jobs to earn the same income. Women are much more likely to work these precarious jobs.

    Prime Minister Scott Morrison has acknowledged that COVID-19’s fallout has been harshest on women.

    Yet his government is pushing an agenda that will ensure there will be less jobs for women, and they’ll be worse paid.

    Economic inclusion of women must be targeted in a long-term, sustained public investment plan that mops up the private sector carnage and lets us build back better.


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

  • Precarity and Job Instability on the Frontlines of NDIS Support Work

    Precarity and Job Instability on the Frontlines of NDIS Support Work

    The national roll-out of the NDIS holds the prospect of a significant enhancement in both the resources allocated to disability services in Australia, and the autonomy and flexibility of service delivery for people with disability. But it also constitutes an enormous logistical and organisational challenge. And the market-based service delivery model built into the NDIS is exacerbating those challenges, by unleashing a widespread fragmentation and casualisation of work in disability services.

    In this new report, researchers document the experience of front-line disability service workers under the NDIS based on first-hand qualitative interviews.

    The report was a joint initiative of two leading academic researchers (Prof. Donna Baines, formerly of the University of Sydney, and Dr. Fiona Macdonald of RMIT) and the Centre for Future Work. Researchers conducted detailed face-to-face interviews with 19 front-line disability service workers, mostly in the Newcastle, NSW region. (Newcastle was one of the locations chosen for NDIS trials, so workers in the region have more experience with the reality of NDIS delivery problems.)

    The interviews indicated 8 major problems negatively affecting the stability, quality and sustainability of work for disability support workers:

    1. The new system is not providing sufficient support for participants with intellectual and other cognitive disabilities, including in designing and managing individual programs of care;
    2. DSWs are experiencing increased instability and precarity in their jobs, elevated levels of mental and physical stress, and irregular hours and incomes;
    3. New workers joining the disability services sector are often less skilled, less trained, less experienced, and sometimes reluctant;
    4. DSWs experience particular challenges working in the private realm of NDIS clients’ homes;
    5. The informal and inconsistent provision of transportation and other necessary functions to NDIS clients results in a significant shift of costs and risks to workers;
    6. DSWs are experiencing increased levels of violence in their work;
    7. Relationships with managers have changed dramatically under the new system, undermining effective supervision, coaching, and training; and
    8. Worker turnover, given the insecurity of work and income and the challenging conditions of work, is extreme.

    The deterioration in job stability and working conditions under the NDIS will inevitably impact on the quality of service experienced by NDIS clients; it will also exacerbate the overarching challenge of recruitment and retention facing disability service providers as they try to attract the 80,000 new full-time equivalent workers required to operate the scaled-up NDIS.

    The researchers conclude with several policy recommendations to improve the quality and stability of work for disability support workers, and the quality of care for participants.


    Full report

    Share

  • Budget 2019-20: Ooops, They Did It Again!

    Budget 2019-20: Ooops, They Did It Again!

    by Jim Stanford

    Share

    You would think that after 5 consecutive years of wage forecasts that wildly overestimated actual experience, the government might have learned from its past errors – and published a wage forecast more in line with reality. But not this government. They are still trying to convince Australian workers, who haven’t seen real average wages rise in over 5 years, that better times are just around the corner. And rosy wage forecasts are helpful in justifying their equally optimistic revenue forecasts: since if Australians are earning more money, they will be paying more taxes!

    So the 2019-20 Commonwealth budget, tabled Tuesday evening by Treasurer Josh Frydenberg, featured another valiant prediction that fast wage growth is indeed still “just around the corner.” Despite a slowdown in wage growth in the last months of 2018, this budget simply replicates last year’s wage forecast – but delayed by one more year. Crucially, there  is no discussion justifying why Australian workers might have confidence in this year’s forecast, when the last five so widely missed the mark (and always in the same direction).

    Our analysis of the 2019-20 Commonwealth budget focuses on the wages crisis facing Australian workers, and challenges the claim that cutting personal tax cuts can somehow compensate workers for the fact that their wages are not growing.

    Annual wage increases generate compounding benefits for workers and their families: since each year’s raise is applied against a larger and larger base. That cannot happen with tax cuts: to the contrary, their incremental effect can only shrink over time (as tax rates get lower and lower). Moreover, tax cuts always come with a significant cost: the loss of foregone public services, income supports and infrastructure that is the inevitable consequence of government’s shrinking revenue base.

    The tax cuts in this budget increase disposable incomes for workers by less than 1% (and by zero for the lowest-wage workers). In contrast, just one year of a normal wage increases delivers several times more benefits. And annual increases over three years (the term of the next government) delivers benefits dozens of times larger.

    Please read and share our full analysis of the 2019-20 budget below, which explains in detail how tax cuts cannot compensate for stagnant wages. You are also invited to view and share this short video summarising the argument (prepared with the help of our colleagues at the Australia Institute).


    Related documents


    2019-20 Commonwealth budget analysis

    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

  • Job Creation Record Contradicts Tax-Cut Ideology

    Job Creation Record Contradicts Tax-Cut Ideology

    by Jim Stanford

    The Australian Bureau of Statistics released its detailed biennial survey of employment arrangements this week (Catalogue 6306.0, “Employee Earnings and Hours“). Once every two years, it takes a deeper dive into various aspects of work life.

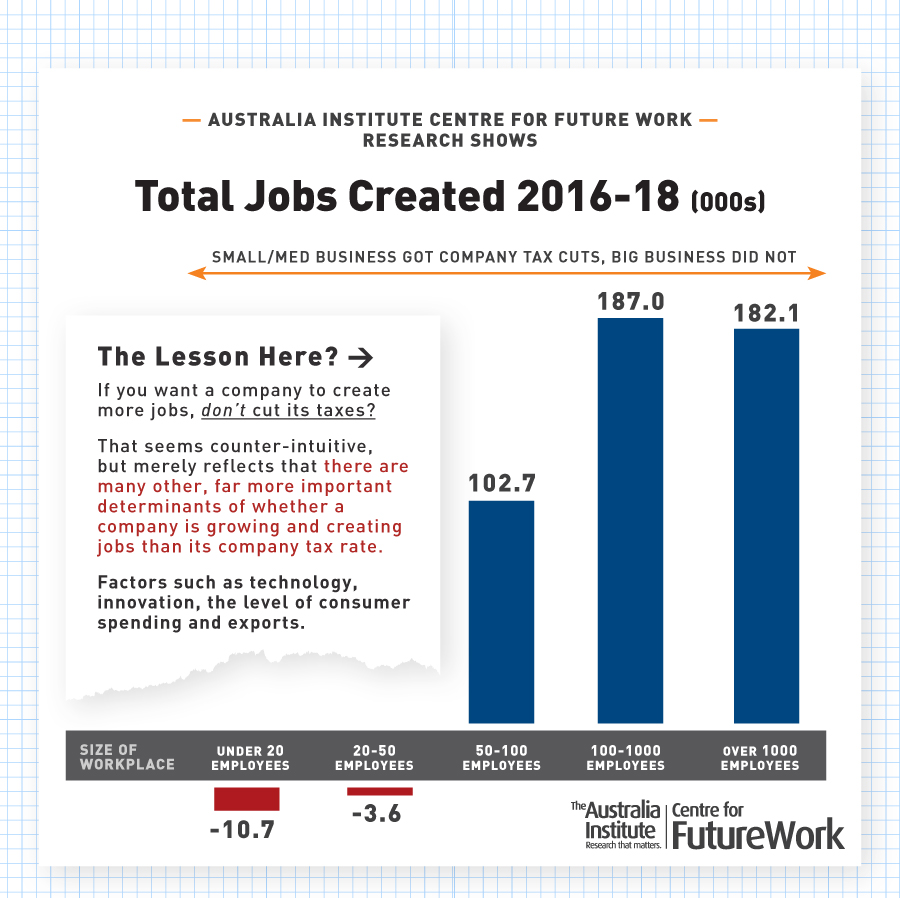
    Buried deep in the dozens of statistical tables was a very surprising breakdown of employment by size of workplace.  It turns out, surprisingly, that Australia’s biggest workplaces (both private firms and public-sector agencies) have been the leaders of job-creation over the last two years.

    This runs against the common refrain that small business is the “engine of growth.”  In fact, workplaces with less than 50 employees actually shed employees (14,000 in total) since 2016.  Curiously, it was only smaller businesses that received the much-vaunted reduction in company tax (from 30 to 27.5 per cent), also beginning in 2016.

    Firm Size and Job Creation

    The tax rate for small and medium-sized businesses began to fall in 2016, first for the smallest firms (with turnover under $2 million), and then for firms with up to $50 million revenue.  The tax is not tied to the number of employees in a business, but the vast majority of firms which have received the tax cut have less than 50 employees.  Yet that is the group that has reduced its workforce since the tax cuts began to be phased in.

    In contrast, very large workplaces (with over 1000 employees) added 182,000 new jobs over the two years.  Workplaces with between 100 and 1000 employees added 187,000.  Very few of those workplaces would have received the reduction in company taxes (since most would exceed the $50 million annual revenue threshold).

    Workplaces between 50 and 100 employees created a net total of 103,000 new jobs between 2016 and 2018.  Some of those firms would have received the tax cut, and some not — depending on the nature of the business and the amount of total turnover generated per employee.

    The data on job-creation by firm size is detailed on Table 13 of Data Cube 1, in the “Downloads” section of the ABS report. The data refers to waged employees, not including owner-managers of businesses.

    The share of small businesses (under 50 employees) in total employment declined by two percentage points — since they were reducing their workforces, while larger companies were growing.  Small businesses (under 50 employees) now account for 34 per cent of all employees, compared to 36 percent in 2016.

    Why would large companies that didn’t get a tax cut create new jobs faster than companies which did benefit from the Coalition tax cuts? (The small business tax cuts are estimated to reduce federal revenues by $29.8 billion over the first decade.) Simple: there are dozens of different factors which determine whether a company is profitable or not, and whether it chooses to grow.  Tax rates are just one of those variables.  Others include:

    • Growth in consumer demand.
    • The company’s investments in product quality, innovation, and design.
    • Production costs.
    • Interest rates and financing costs.
    • Business confidence and expectations.
    • Management capacity.
    • International competition.

    Trends in all these other factors can easily overwhelm the marginal impact of lower tax rates.  Small business sales in particular have been held back by stagnant wages among Australian workers.  Even companies which experience higher profits due to lower tax rates may choose to simply accumulate those profits, or pay them out to shareholders in dividends and share buy-backs (instead of expanding payrolls).  Empirical evidence shows this has been the dominant impact of U.S. business tax cuts implemented by Donald Trump.

    Changes in tax rates can even have offsetting effects which undermine business conditions and hence reduce job-creation: if the revenue lost to tax cuts results in corresponding reductions in government program spending or infrastructure investments (as seems likely), then overall business conditions might be weakened, not strengthened.

    The reduction in employment by the businesses which most benefited from the expensive business tax cuts over the past two years should lead policy-makers of all persuasions to reconsider the argument that this is an effective way to stimulate growth and job-creation. However, in October the government announced it wanted to accelerate the next stages of the small business tax cuts — taking the rate down to 25 per cent five years faster than originally planned.

    So far, the policy is akin to shooting oneself in the foot.  Instead of reloading the gun to do it again even sooner, perhaps this is a good time to reconsider whether the strategy makes any sense at all.


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Dutton’s nuclear push will cost renewable jobs

    by Charlie Joyce

    Dutton’s nuclear push will cost renewable jobs As Australia’s federal election campaign has finally begun, opposition leader Peter Dutton’s proposal to spend hundreds of billions in public money to build seven nuclear power plants across the country has been carefully scrutinized. The technological unfeasibility, staggering cost, and scant detail of the Coalition’s nuclear proposal have

  • Centre for Future Work at #ACTUCongress18

    Centre for Future Work at #ACTUCongress18

    by Jim Stanford

    Share

    Trade unionists from across Australia are gathering in Brisbane this week for the 2018 Congress of the Australian Council of Trade Unions. And the Centre for Future Work will be there!

    Come and check out our information booth in the exhibitors’ area: meet our staff, learn more about our work, and sign up for updates.

    Our Director Jim Stanford will be presenting as part of a session on The Future of Work (good title!), Tuesday July 17 at 2:15 pm in conference room P1.

    And we will be distributing copies of a brochure with links to some of our most recent research (attached below).

    We are glad that our research can support the campaign to #ChangeTheRules!


    Related documents


    Brochure

    Related research

    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

  • Scare Tactics for Corporate Tax Cuts Do Not Stand Fact Checks

    Scare Tactics for Corporate Tax Cuts Do Not Stand Fact Checks

    by Anis Chowdhury

    Share

    In the wake of the Trump Administration’s success in pushing a major company tax cut through the U.S. Congress, the Australian Treasurer has stepped up his calls for reduced company taxes here. He claims Australia will bypass the growth-inducing benefits of these tax cuts, but Dr. Anis Chowdhury, Associate of the Centre for Future Work, has compiled the economic evidence.  The U.S. experience shows no statistical evidence of any “trickle-down” growth dividend from company tax cuts.

    “Trump tax cuts: Scott Morrison warns business will abandon Australia while we are at the beach” was the Sydney Morning Herald headline, reporting on the Coalition Government’s scare tactics to press through its tax cuts gift for business.  The Treasurer used the opportunity of the Trump tax cuts to issue this “dire” warning. However, his claim does not withstand some basic empirical scrutiny.

    Fact 1: Australia is not a high tax country

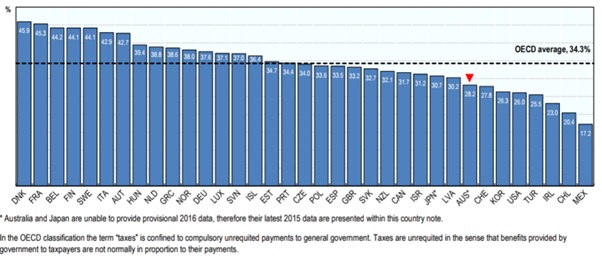
    Our overall tax take is one of the lowest among the 35 OECD countries. If Mr. Morrison was correct, then by now there should have been a tsunami of investment flowing here from 27 OECD countries with higher tax-GDP ratios than that of Australia’s 28.2% in 2016. Australia’s overall tax ratio is well below the OECD average of 34%, and also below neighbouring New Zealand’s tax take of 32.1% of GDP.

    Here are reported tax ratios for 27 OECD countries, 2016.

    OECD Tax Shares
    Source: Revenue Statistics 2017 – Australia; https://www.oecd.org/tax/revenue-statistics-australia.pdf

    Fact 2: Australia’s effective corporate tax is far below its statutory 30% rate

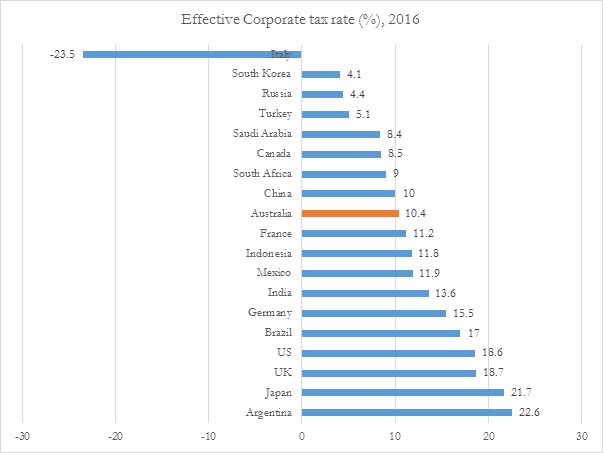
    Australian companies may seem to face a higher statutory corporate tax rate, but once they go through all their deductions and credits they don’t end up paying an unusually high amount compared to companies in other nations. The average effective rate (10.4%) is barely one-third the statutory rate. In fact, more than a third of large companies did not pay any corporate taxes in 2016 according to the recently released ATO data.

    Effective vs Statutory Tax Rates
    Source: National Public Radio, based on US Congressional Budget Office data; https://www.npr.org/2017/08/07/541797699/fact-check-does-the-u-s-have-the-highest-corporate-tax-rate-in-the-world

    Fact 3: Tax is low on companies’ lists of factors influencing investment location decision

    For example, the OECD noted, “it is not always clear that a tax reduction is required (or is able) to attract FDI. Where a higher corporate tax burden is matched by well-developed infrastructure, public services and other host country attributes attractive to business… tax competition from relatively low-tax countries not offering similar advantages may not seriously affect location choice. Indeed, a number of large OECD countries with relatively high effective tax rates are very successful in attracting FDI.”

    This is corroborated by the most recent World Bank survey of enterprises, which found that tax incentives are not high on the list of critical factors affecting inflows of foreign direct investment. The IMF’s recent research also reports that the net impact of corporate tax cuts to incentivise private investment is quite often negative on government revenues.  The pre-tax profitability of Australian businesses has also tended to exceed that in other countries, and this is surely more important in motivating investment flows.

    Fact 4: Rigorous studies of past US tax cuts did not find a positive link between tax cuts and economic or employment growth

    For example, the oft-cited examples of the Reagan or Bush tax cuts do not in fact demonstrate that tax cuts cause growth.  Admitted by President Reagan’s former chief economist, Martin Feldstein, the vast majority of growth during the Reagan era was due to expansionary monetary policy that slashed interest rates massively to help the economy bounce back from a severe recession in 1982.  Increased defence spending and an expanded labour force due to an influx of baby boomers also boosted the economy. In another study with Doug Elmendorf, the former Congressional Budget Office Director, Martin Feldstein found no evidence that the 1981 tax cuts increased employment.

    The 2001 and 2003 Bush tax cuts also failed to spur growth. Between 2001 and 2007 the economy grew at a lacklustre pace—real per-capita income rose by 1.5% annually, compared to 2.3% over the 1950-2001 period. Interestingly, the two sectors that grew most rapidly in this period were housing and finance, which were not affected by the 2001 and 2003 tax cuts.  Moreover, by 2006, prime-age males were working the same hours as in 2000 (before the tax cuts), and women were working less – both facts inconsistent with the view that lower tax rates raise labour supply.

    Fact 5: The most infamous case of tax cuts in the US State of Kansas was a colossal failure

    Governor Sam Brownback promised that a moderate tax cut for individuals and a big tax cut for businesses would be “like a shot of adrenaline into the heart of the Kansas economy.”  Unfortunately, however, despite his 2012 tax cuts, the Kansas economy remained moribund, while neighbouring states surged ahead. In the process, the Kansas state budget was left in tatters. No wonder that the Republican-led state legislature reversed most of Brownback’s tax cuts in the face of poor growth and pressing public spending needs.

    Therefore, if Mr. Morrison is serious about repairing the budget, or stimulating growth and employment, then he should be concentrating on raising more revenues (not less) and investing in the nation – instead of cutting basic services to fund his tax cuts for the rich. He should be looking at the facts, instead of resorting to scare tactics.


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Centre For Future Work to evolve into standalone entity

    The Centre for Future Work was established by the Australia Institute in 2016 to conduct and publish progressive economic research on work, employment, and labour markets. Supported by the Australian Union movement, the centre produced cutting edge research and led the national conversation on economic issues facing working people: including the future of jobs, wages

  • Budget Wrap-Up

    Budget Wrap-Up

    Share

    Commonwealth Treasurer Scott Morrison tabled his 2017-18 budget in Parliament House on May 9, and the Centre for Future Work’s Director Jim Stanford was there in the lock-up to analyse its likely impacts. Here are some of our main impressions and comments:

    Wage Growth and Deficit Reduction

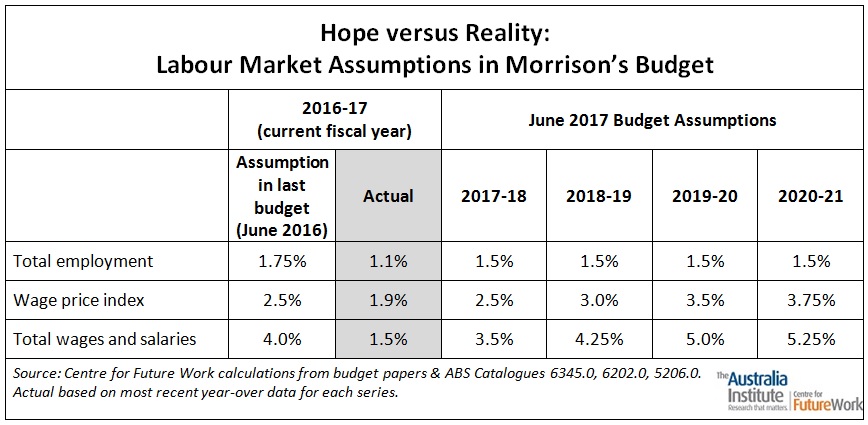
    Several commentators have highlighted the budget’s highly optimistic assumptions regarding future job-creation and wage growth incorporated into the budget forecast. The government is anticipating an immediate and sustained acceleration of all of the factors that contribute to the wage base for tax revenue: faster job-creation, significantly faster growth in hourly pay, and dramatically faster growth in total wages and salaries.

    Back in the real world, the labour market has been underperforming on ALL THREE of those components: slow job-growth, record slow growth in hourly wages, and falling weekly hours of work (due to the dramatic expansion of part-time and irregular work). For all of these reasons, total wages and salaries paid out in the economy (which forms the major basis for personal tax collections, both income and GST) actually declined in the latest quarter of GDP (Dec 2016).
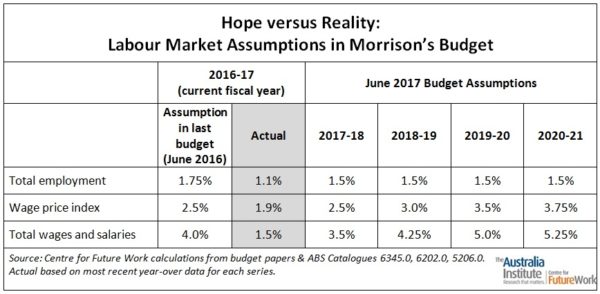
    This table summarises the main wage assumptions in Mr. Morrison’s budget, contrasting them to the latest actual figures on each of the three criteria. The last budget (2016-17) missed the mark badly on all three criteria — but the likely undershooting error will be huge by the end of this budget’s forward estimates, unless there is a dramatic and sustained acceleration of employment and wages growth.

    Director Jim Stanford pointed out in this Huffington Post column that the current weakness in Australian wages is not an accident, nor is it likely to reverse automatically. Chronically weak aggregate labour market conditions, combined with structural attacks on the institutions that support wages (including unions, minimum wages, penalty rates, and others), have caused the unprecedented stagnation of wage incomes in Australia. The macroeconomic consequences of this state of affairs have been widely acknowledged — even by the government itself. (Mr. Morrison himself spoke recently of his concern with the impact of wage stagnation on his own budget targets.)

    As Stanford put it in his Huffington Post commentary, the contradiction between the government’s wage-suppressing economic and regulatory policies, and its hope that wage growth will nevertheless power the way to a balanced budget, is both glaring and unsustainable:

    “[Morrison’s] rose-coloured labour market assumptions will be sabotaged by his own government’s continuing war on workers and wages. And that’s one important reason why his hopeful deficit targets will not be realised.”

    General Optimism Regarding Revenue

    The budget’s optimistic wage growth assumptions are just one factor behind an overall revenue forecast that is downright ebullient. The main force behind the projected return to a balanced budget is an enormous assumed increase in tax revenues — very ironic coming from a government that regularly derides the alleged “tax-and-spend” procilivities of its opponents. Over the four years of the forward projection, annual revenues are expected to expand $120 billion by 2020-21 (or 30 percent). As a share of GDP, revenues are expected to swell by 2.2 percentage points, reaching the highest share (25.4% of GDP) since the peak of the mining boom (in 2005-06).

    There is no clear explanation of where these huge new revenues come from – especially given the revenue-reducing effect of other budget measures, including company tax cuts, the elimination of the deficit repair levy for high-income earners, last year’s bracket adjustments, and others. There are some modest revenue measures in the budget: including the 0.5% Medicare levy increase (after 2019), the levy on bank liabilities, and a new levy on employers who hire migrant labour. But those policy decisions account for just 6.5% of all new revenues assumed to be received over the coming 4 years — and they will be more than offset by the revenue losses from the other measures (especially the company tax cuts).

    If revenues stay constant as a share of GDP (instead of magically growing), the budget will be $45 billion short in 2020-21 – and the forecast small surplus will evaporate into a large continuing deficit. Indeed, as our colleagues at the Australia Institute have pointed out, this budget marks the fourth consecutive four-year LNP timetable for balancing the budget. The government’s tough talk on the dangers of deficit-financing, and stated intention to quickly achieve balance, have proven hollow. Many of its proposed spending cutbacks have been successfully resisted by community campaigning. And its rosy revenue forecasts have been consistently unfounded. There is no reason to believe this year’s four-year deficit elimination timetable is any more realistic than the last three.

    Robbing Peter to Pay Paul

    On the spending side, the government is announcing some modest new spending initiatives, totaling $9 billion over 4 years.

    But at the same time, they are announcing spending cuts to a wide range of programs (including higher education, welfare, and civil servants) – totaling $10 billion over the same period.

    The net impact of new policy decisions on spending is therefore $1 billion in the negative. Despite the promise of “better times” in the future, the government’s discretionary actions will reduce aggregate funding for the programs that Australians depend on.

    A Target Everyone Can Love: The Big Banks

    The government’s new 6 basis point “levy” on bank liabilities (ie. on outstanding loans) is forecast to raise $6.2 billion over 4 years.

    Many analysts believe this tax will be passed on to borrowers (since it is defined as a proportion of lending), and the government has not provided a convincing refutation of this concern. The levy is equivalent to a slight increase in the cost of capital for new lending. (In fact, this new “levy” is smaller than recent increases in interest rates which the banks have already passed on to their borrowers.)

    The government’s claim that the ACCC, with increased funding, will ensure the banks do not pass on the costs of the levy is laughable — as is its claims that competition from smaller banks will keep the big banks in line. Unless there is outright collusion and price-setting between the banks (something that is rare and unnecessary anyway), there is nothing illegal about passing on higher costs to consumers. Indeed, the ability to do this is precisely what explains the banks’ consistent above-normal profits (earning return on equity of 15 percent or more each and every year).

    At any rate, once the banks start to benefit from the full 5% reduction in their own corporate taxes (by 2026-27), they will still be saving billions each year on a net basis.

    The eminent economist Prof. Geoffrey Harcourt, a good friend of our Centre, put it this way in a blog comment:

    “The discussions on the levy/tax on the big four banks in the 2017 budget are often hysterical and beside the point. Because banks play an essential role in the running of the economy, they need protection through a guarantee from the government. Because of their oligopolistic market structure, they are in a privileged position to make large profits, a portion of which reflects their necessary privileged position, rather than any merit of their own. Common sense suggests that it would be both efficient and equitable that the banks be allowed to receive, say, the average rate of profits ruling in the economy as a whole without being taxed differently than any other form of enterprise in Australia. If their overall rates of profit are greater than the average – which they certainly are – the differences between the two sets of rates should be subject to a higher rate of tax so that the community at large receives a return on the privileged position the banks have been necessarily granted. The proposed levy is roughly akin to this proposal, which is tackling an equitable puzzle. It should not, in principle, be related to what is happening to the budget overall and especially to the sizes of any deficits or surpluses. These should reflect the outcome of attempting to meet the real aims of good government starting with achieving and sustaining full employment and sustainable growth.”

    Infrastructure Spending: Show Us the Money

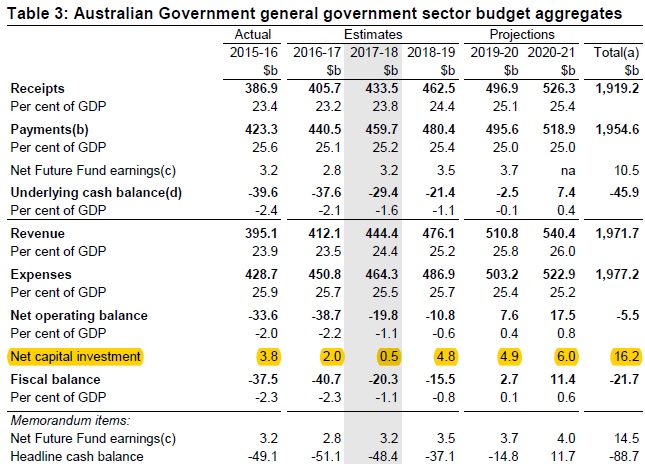
    The government is boasting of $75 billion in infrastructure funding and financing over the next ten years. It is impossible to know how much of this represents new funds, nor when the funds would be delivered. Keep in mind that at present the government already spends over $18 billion per year on capital (or $200 billion over the next decade): both on new projects, and offsetting the wear and tear of existing assets. So the $75 billion “plan” ($7.5 billion per year) may or may not represent a substantial ramp-up in new capital spending by Canberra.

    In fact, the details of the budget do not seem to indicate any enormous expansion in capital spending. Net capital spending (after depreciation) is projected to decline in 2017-18: to just $0.5 billion, the smallest since 2002-03. (See Budget Table 3, reprinted below.) In essence, in the first year of the budget, the government will spend barely enough to offset depreciation of existing assets.
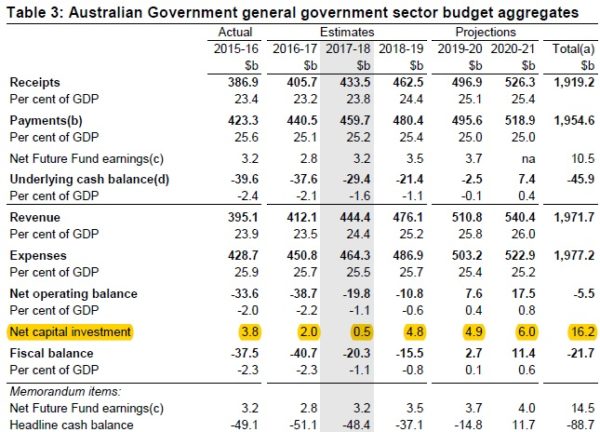
    Net investment grows in later years, but not dramatically. And as a share of GDP, net capital spending by the Commonwealth is projected to average just 0.2% of GDP over the forward projections. Over the last ten years, in contrast, it averaged 0.25% of GDP. In other words, under this budget, net Commonwealth capital spending will actually shrink relative to the economy.

    It is easy to come up with “big numbers” when talking about infrastructure programs (especially by summing totals over many years), and associated ribbon-cutting ceremonies will attract much attention. But there is no concrete evidence that this budget will accomplish the real and sustained increase in Commonwealth government capital spending that is needed. Commonwealth capital spending has declined in recent years compared to earlier decades, and there is no evidence that this budget will change that trend.

    Migrant Labour and Apprentices

    The government is imposing a new “head tax” on employers who hire foreign migrants: $1200 to $1800 per year per head for temporary migrants, and $3000 to $5000 for each permanent migrant (on a one-time basis). The revenues from this levy will be used to fund support for apprenticeships in conjunction with the states, to a total of $1.2 billion over the next 4 years.

    Funding skill programs through a tax on migrant labour is not an effective way to rebuild Australia’s battered vocational education system – nor is it an effective way to regulate employers’ over-reliance on temporary foreign migrants (rather than recruiting and training Australian workers). Indeed, the scale of revenues anticipated by the government suggests that incoming migrant labour will continue to constitute a major force in Australia’s labour market.

    Effectively regulating and reforming Australia’s migrant labour system – limiting its use to classifications where skilled workers are truly unavailable, and ensuring that migrant workers are entitled to the same protections as all other workers – would in fact undermine the head tax revenues that the government is now counting on.

    Check Out The Australia Institute’s Budget Analysis

    Our colleagues at the Australia Institute have also generated some useful and punchy commentary on the budget: see it all (including a hilarious podcast with economists Richard Denniss and Matt Grudnoff) on the Institute’s Budget Wrap page.


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Centre For Future Work to evolve into standalone entity

    The Centre for Future Work was established by the Australia Institute in 2016 to conduct and publish progressive economic research on work, employment, and labour markets. Supported by the Australian Union movement, the centre produced cutting edge research and led the national conversation on economic issues facing working people: including the future of jobs, wages

  • Bracket Creep Is A Phoney Menace

    Originally published in New Matilda on May 11, 2016

    For someone who piously bemoans an “us versus them” mentality in political culture, Treasurer Scott Morrison certainly drove a deep wedge into the social fabric with one of the centrepieces of his budget. There are four thresholds in the personal income tax system; Morrison chose to increase one of them, supposedly to offset the insidious effects of “bracket creep.” The third threshold will be raised from $80,000 to $87,000.

    Other thresholds don’t change. Taxpayers making over $80,000 will thus get a small saving ($6 per week at most). Those who make less, get nothing.

    It’s not the most expensive tax cut in the budget. It will cost an estimated $800 million in the first year – barely half the $1.5 billion lost annually by cancelling the deficit repair levy on incomes over $180,000, and far less than the ultimate cost of Morrison’s company tax cuts. But it is the most transparent and easy to understand of all the budget’s tax measures. And it will spark the most gossip around the water-cooler. Who makes over $80,000 per year, anyway? And who makes less? It’s hard to imagine a more “us versus them” tax policy.

    The Treasurer’s own rhetoric reinforces this schism: he says it will “reward hard working Australians,” encourage them to work overtime, take more shifts, and accept a promotion. The clear implication is that people making less than $80,000 are not interested in working more hours or taking promotions. Indeed, they aren’t even “hard working” in the Treasurer’s terms, and hence don’t merit protection from “creeping” taxes.

    The Treasurer tried, but failed, to define the measure as one that benefits “average” wage-earners. Mean annual earnings for a full-time worker employed year-round are indeed near $80,000. But this does not remotely describe the typical Australian. First off, the mathematical “average” is skewed upward by super-high incomes at the top of the income ladder; the median full-time wage (received by the full-time worker in the exact middle of the distribution) is $10,000 lower than the average, and well below the threshold. Likewise, women (even those employed full-time year-round) earn $10,000 less than the mathematical mean.

    Federal Treasurer Scott Morrison delivering his first budget, in 2016.
    Federal Treasurer Scott Morrison delivering his first budget, in 2016.

    But the bigger problem is that a shrinking share of Australians have full-time permanent jobs to start with. Part-time work now accounts for almost one in three jobs – the highest on record.  And labour hire, temporary contract, and other forms of precarious work are increasingly the norm. Very few of those workers earn anywhere near $80,000. At most about one in four Australian workers (and perhaps 15 per cent of all tax-filers) will get the full $6 per week saving.

    The whole concept of “bracket creep” is itself as misleading as Morrison’s maths. He says taxpayers are “pushed” into higher tax brackets by rising incomes, constituting a punitive and underhanded tax grab. But this description merits some careful second thought.

    There are two different reasons why a worker’s income might rise. One is pure inflation, experienced across all wages and prices. In that case, nothing “real” changes, and a higher tax rate might seem unfair (although we should remember that the cost of many government programs also grows with inflation, and someone has to pay for that).

    Alternatively, it might be changes in a worker’s real income that qualify them for the next bracket. If they worked more hours or took a promotion (as the Treasurer urges), then their real income rises, and so does their tax. That’s not bracket creep, and there’s nothing “underhanded” about it. In fact, that is the whole point of a personal income tax system in which tax rates depend on income.

    Moral panic over bracket creep is all the more ironic given the unprecedented stagnation in Australian wages, reflecting sustained weakness in the job market. Average weekly earnings in the private sector are growing at their slowest pace in history: under 1 per cent per year (slower than inflation). The budget itself acknowledged this is badly hurting Commonwealth revenues. With wages going nowhere fast, this is hardly the time in history to make a mountain out of a bracket creep molehill.

    If the government truly wanted to prevent inflation from distorting taxes, it could simply index all parameters in the tax code to consumer prices (as other countries, like the U.S. and Canada, have done). Then all thresholds, not just the one cherry-picked by Morrison, would rise 1.3 per cent this year, the same as year-over-year inflation. But that would depoliticise the whole process, hardly acceptable in a year when every single clause of the budget is focused on getting the government re-elected. So Morrison picked one politically-potent threshold, lifted it seven times faster than inflation, and left everyone else to get “creeped.”

    Previous ad-hoc increases to thresholds have lifted them far faster than inflation. In fact, with this latest increase, the third tax threshold will have risen twice as much as inflation since 2003. Combined with rate reductions also targeted at top brackets during that time, government revenues have been undermined badly, and the upward redistribution of after-tax income has been exacerbated.

    In short, the politics of Morrison’s over/under game are hard to understand. He will deliver a tiny benefit to less than one in four employed workers, and barely one in seven tax-filers. Most Australians won’t get a cent. But the economics are even worse. His divisive and false anti-tax narrative undermines the long-run stability of the government’s revenue base, damages public services, and reinforces inequality.


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Centre For Future Work to evolve into standalone entity

    The Centre for Future Work was established by the Australia Institute in 2016 to conduct and publish progressive economic research on work, employment, and labour markets. Supported by the Australian Union movement, the centre produced cutting edge research and led the national conversation on economic issues facing working people: including the future of jobs, wages

  • 6 Reasons to Be Skeptical of Debt-Phobia

    6 Reasons to Be Skeptical of Debt-Phobia

    by Jim Stanford

    In the lead-up to tomorrow’s pre-election Commonwealth budget, much has been written about the need to quickly eliminate the government’s deficit, and reduce its accumulated debt.  The standard shibboleths are being liberally invoked: government must face hard truths and learn to live within its means; government must balance its budget (just like households do); debt-raters will punish us for our profligacy; and more.  Pumping up fear of government debt is always an essential step in preparing the public to accept cutbacks in essential public services.   And with Australians heading to the polls, the tough-love imagery serves another function: instilling fear that a change in government, at such a fragile time, would threaten the “stability” of Australia’s economy.

    However, this well-worn line of rhetoric will fit uncomfortably for the Coalition government, given its indecisive and contradictory approach to fiscal policy while in office.  The deficit has gotten bigger, not smaller, on their watch, despite the destructive and unnecessary cutbacks in public services imposed in their first budget.  Their response to Australia’s fiscal and economic problems has consisted mostly of floating one half-formed trial balloon after another (from raising the GST to transferring income tax powers to the states to cutting corporate taxes), with no systematic analysis or framework.  And their ideological desire to invoke a phony debt “crisis” as an excuse for ratcheting down spending will conflict with another, more immediate priority: throwing around new money (or at least announcements of new money), especially in marginal electorates, in hopes of buying their way back into office.

    In short, the politics of debt and deficits will be both intense and complicated in the coming weeks.  To help inoculate Australians against this hysteria, here are six important facts about public debt, what it is – and what it isn’t.

    1. Australia’s public debt is relatively small

    Despite annual deficits incurred since the GFC, Australia’s accumulated government debt is still small by international standards.  Debt can be measured on a gross or net basis; gross debt counts total outstanding borrowing, while net debt deducts the value of financial assets which the government also possesses.  Gross debt for all levels of government equaled 44% of Australian GDP at the end of 2015 (according to the OECD).  That was the 5th lowest indebtedness of any of the 34 OECD countries (see table below), equal to about one-third the average level experienced across the OECD.  Moreover, despite recent deficits, the growth of debt in Australia was considerably slower than in most other OECD countries.  Of course, having low debt in and of itself does not justify increasing it.  But given the universal fiscal challenges that have faced industrial countries since the GFC, Australia’s debt challenge is both unsurprising and relatively mild.

    Australia’s Debt in International Context: General Government (all levels) Gross Financial Liabilities (%GDP) 
    2015 10-yr. Change
    Australia 44.2% +22.4 pts
    U.S. 110.6% +43.7 pts
    Japan 229.2% +59.7 pts
    France 120.1% +38.3 pts
    Germany 78.5% +8.1 pts
    Italy 160.7% +41.8 pts
    U.K. 116.4% +60.3 pts
    Canada 94.8% +19.0 pts
    OECD Average 115.2% +36.3 pts
    Source: Author’s calculations from OECD Economic Outlook #98, Nov.2015.

    2. A government debt is matched by an asset

    Australians aren’t “poorer” because their government accumulates a debt.  Any rise in government debt is mirrored by an increase in some offsetting asset.  This is true in both accounting terms, and in real economic terms.  For example, government typically issues a bond (or some other financial instrument) to finance a deficit.  But that bond also constitutes an asset in the investment portfolio of whoever lent the government money.  Most Australian government debt is owned by Australians.  In fact, investors increasingly appreciate the opportunity to invest in government bonds, because they are safer than other assets at a time of financial uncertainty.  (That investor interest is one reason interest rates on government debt are so low.)  So government debt translates into someone else’s wealth – usually someone in Australia.

    This match between liabilities and assets is also visible in concrete economic terms – especially when new debt is issued to construct a real, long-lasting capital asset (like a road, a transit system, a school, or a hospital).  In this case, the matching asset is owned by government itself, and so its own net worth won’t change much at all: it takes on a new debt, but also has a new asset.  For budgetary purposes, the government must account for the gradual wear-and-tear of that asset (called depreciation), which appears as a cost item on the budget.  But it hasn’t “lost” the money it raised through the new debt: it invested it, and that investment carries both financial and social value.

    3. Other sectors of society borrow much more than government

    Tired rhetoric about how governments need to act “more like households” is especially ironic, given that households are by far the most indebted sector in Australian society.  Household net debts equal close to 125% of GDP – or around 4 times the net debt of government (all levels), according to data from the Bank for International Settlements.  It is factually wrong to claim that “households balance their budgets,” and therefore governments must do the same.  Households borrow regularly – and thanks to overinflated housing prices and stagnant wages, that borrowing is growing rapidly.  The same is true of business: net debts of non-financial corporations are more than twice the net debt of government (see chart).

    In fact, it is quite rational for households and businesses to borrow, when needed to fund purchase of long-run productive assets (like a house or a car for consumers, or a factory or new technology for a business).  Business leaders know that rational, prudent borrowing will enhance the profitability of a corporation.  Indeed, any CEO who said paying off all company debt was the top priority of the firm would be chased from office by directors and shareholders (who would understand the pledge was irrational and superstitious).  Following exactly the same logic, government debt can be rational and productive – especially (but not only) when it is associated with the acquisition of long-run productive assets (like infrastructure).  Close to two-thirds of the Commonwealth government’s 2015/16 deficit (projected to be $36 billion) is associated with capital spending, including $11 billion in capital transfers to lower levels of government and $12 billion in net investment in Commonwealth non-financial assets.  Contrary to the rhetoric, Australians do largely cover the cost of current public services with their current tax payments.  Government borrowing is primarily required to fund capital spending.

    4. Interest rates are low, and falling

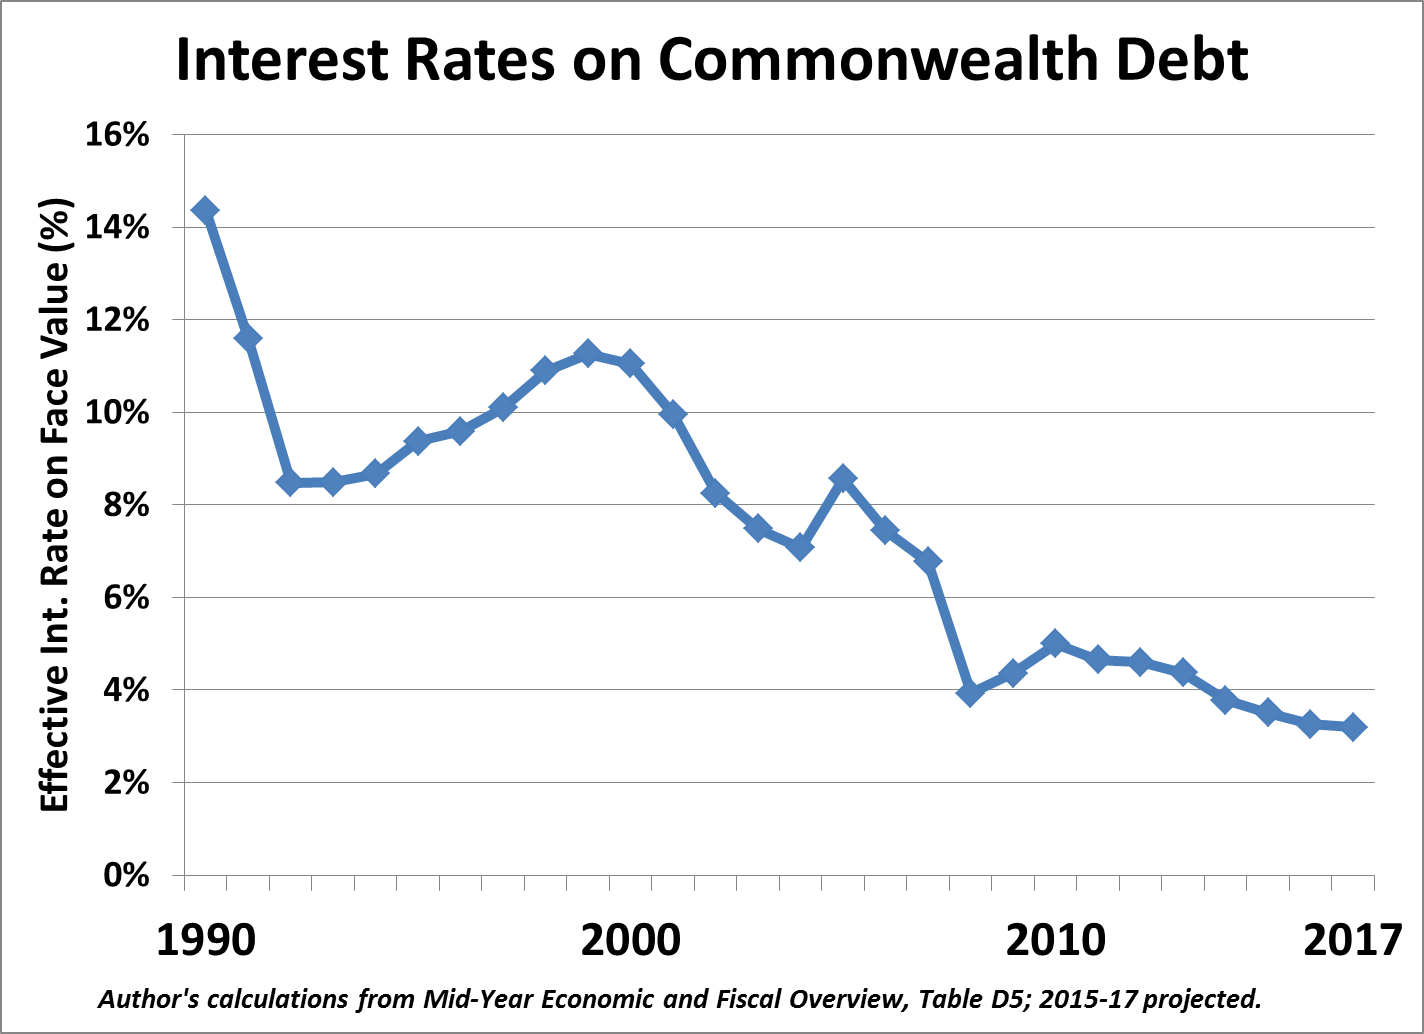
    The cost of public borrowing has fallen dramatically as a result of the decline in Australian and global interest rates since the GFC (see chart).  Indeed, the two factors are connected: large government deficits resulted primarily from underlying economic weakness (this is true in Australia, like elsewhere in the industrialized world), which in turn bro8ught about low interest rates (via both central banks and private financial markets).  These very low interest rates mean that the cost-benefit decision associated with any new government borrowing has been fundamentally altered, in favour of borrowing.

    Current interest rates are likely to stay low for many years to come, given the continuing failure of the global economy to regain consistent momentum, the slowdown in China, and other factors.  (In fact, it is possible that the Reserve Bank of Australia may soon cut its interest rate further, below its current record-low 2% level, due to weak growth and signs of deflation here in Australia.)  Ten-year Commonwealth bonds can presently be floated to private investors for little more than 2% interest (close to zero in real after-inflation terms).  If government can borrow for what is effectively zero interest, and put that money to work in the real economy doing useful things (including both infrastructure and public services), then it is irrational to let old-fashioned balanced-budget mythology stand in the way.

    Even if current interest rates do not fall any further, the average effective interest rate paid on overall public debt will continue to fall for years to come.  The current average effective rate paid on Commonwealth debt (about 3.5% last year) reflects the weighted average paid on all maturities of debt.  As past debts come due, they are refinanced at now-much-lower interest rates (those prevailing on new issues of bonds).  That will pull down the average weighted interest rate for several years into the future – even if the rate on new issues stabilizes or increases somewhat.  Consider that new ten-year bonds can be issued for less than half the interest rate paid a decade ago.  The refinancing of those bonds will generate enormous future interest savings for government (equivalent to home-owners who re-mortgage their homes to benefit from the decline in household lending rates).

    This is why the economic burden of public debt servicing is not growing, even though the debt is.  Government budget projections forecast debt service remaining at between 0.9 and 1.0% of GDP for the next 5 years, with the effect of rising debt offset by falling interest rates.  And those government projections likely overestimate true interest costs (partly for political reasons).  For example, the December 2015 MYEFO update assumes a significant increase in interest rates in the coming year (its near-term interest rate assumption was 0.3 points higher than the assumption used in last year’s budget); ongoing global and domestic economic weakness makes that highly unlikely.

    5. The debt/GDP ratio is a more meaningful fiscal constraint than a balanced budget

    Fear-mongers think that by talking about public debt in “big numbers,” the fright value of their dire forecasts can be magnified accordingly.  But all macroeconomic aggregates are measured in big numbers.  And what’s more important than the absolute size of debt, is the government’s capacity to service that debt.  That, in turn, depends on the flow of government revenues, which in turn is driven primarily by overall economic growth.  That’s why economists prefer to evaluate public debt relative to GDP (called the “debt ratio”).  Even this ratio can overstate the real burden of debt, in times (like now) when interest rates are low and falling.

    Avoiding a lasting, uncontrolled rise in the debt/GDP ratio is a more meaningful fiscal constraint on government, than trying to balance a budget in any particular year.  Economists do not agree on a maximum “acceptable” limit for that ratio.  But most agree it cannot rise forever.  (Some economists argue that there is no limit on a government’s ability to issue sovereign debt denominated in its own currency, and the recent experience of countries like Japan – whose debt ratio is five times Australia’s – is consistent with that view.)

    At any rate, Australia is far away from any feasible “ceiling” on public debt relative to GDP.  And remember, like any ratio, the debt/GDP ratio has both a numerator and denominator: growing the denominator is as effective as shrinking the numerator, if the goal is reducing the value of the combined ratio.  In this regard, the stagnation in Australia’s nominal GDP in recent years has been more damaging to the trajectory of the debt ratio, as has the addition of debt through continued deficits.  The government’s policy focus should be on expanding economic activity (and the jobs and incomes that go with it), rather than suppressing the deficit with austerity measures (which have the unintended consequence of undermining growth and hence the economy’s ability to service a given amount of debt).

    6. The government can incur moderate deficits every year, yet still stabilize its debt burden

    A related and under-appreciated countervailing argument is to note that government can run a medium-sized deficit on an ongoing basis, and yet experience no increase in the debt/GDP ratio at all – so long as the economy is progressing at a normal pace.  A deficit adds to the numerator of the ratio, while economic growth expands the denominator.  So long as both are expanding at roughly the same rate, the ratio will not be changed.  (Our reference to economic expansion envisions more jobs and incomes across the economy, including in the public sector, and with due attention to the need for environmental sustainability.)  This basic arithmetic provides government with an additional degree of maneuverability in financing essential services and investments, without unduly increasing the debt ratio.

    A simple numerical example helps to illustrate the point in Australia’s context.  A healthy economy should be expanding by at least 5-6 percent per year in nominal terms: divided roughly equally between inflation (given the RBA’s 2-3 percent inflation target) and greater output of real goods and services (driven by both population and productivity).  The Commonwealth’s current net debt ratio is slightly below 20 percent of GDP.  With a healthy economic expansion, the government could incur an annual deficit of 1-1.25 percent of GDP (or close to $20 billion per year) but still stabilize the debt ratio below that 20 percent benchmark.  And there is nothing magical about a 20% debt ratio; if Australians were willing to tolerate a larger steady-state debt ratio, then the size of this annual permissible deficit would be correspondingly higher.  All this merely reinforces the need for government to focus on supporting job-creation and incomes, not balancing its budget – and confirms that ample fiscal space is indeed available for the Commonwealth to fund public services and infrastructure spending (with the fringe benefit of reinforcing strong job creation that should be their top priority).


    You might also like

    Commonwealth Budget 2025-2026: Our analysis

    by Fiona Macdonald

    The Centre for Future Work’s research team has analysed the Commonwealth Government’s budget, focusing on key areas for workers, working lives, and labour markets. As expected with a Federal election looming, the budget is not a horror one of austerity. However, the 2025-2026 budget is characterised by the absence of any significant initiatives. There is

    Centre For Future Work to evolve into standalone entity

    The Centre for Future Work was established by the Australia Institute in 2016 to conduct and publish progressive economic research on work, employment, and labour markets. Supported by the Australian Union movement, the centre produced cutting edge research and led the national conversation on economic issues facing working people: including the future of jobs, wages